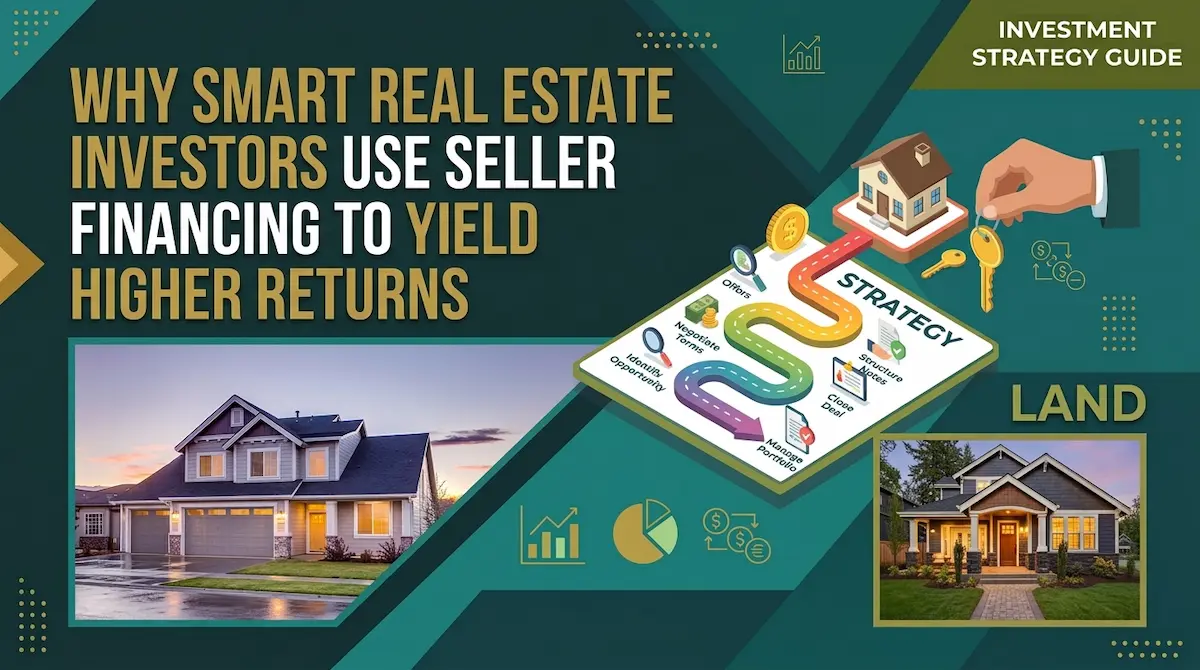
Owner financing (or seller financing) allows real estate buyers to finance a property purchase directly through the seller rather than a traditional institutional lender. For smart real estate investors, offering flexible owner financing terms transforms real estate assets into high-yielding, predictable cash-flow streams. By stepping into the role of the bank, sellers eliminate conventional closing delays, earn interest income above prevailing market rates, lower upfront capital expenditures, and spread capital gains tax liabilities over multiple years.
Introduction:
The real estate landscape is undergoing a permanent shift. As traditional institutional mortgage rates fluctuate and banking guidelines tighten, real estate investors are finding that standard debt models frequently squeeze profit margins. Institutional lending delays, heavy underwriting requirements, and high closing fees routinely eat into projected cash flows.
To overcome these obstacles, sophisticated investors are bypassing conventional banking channels altogether. Instead of acting purely as traditional landlords or home sellers, savvy capital allocators are stepping into the role of the bank.
By structuring strategic owner financing terms, real estate investors are generating superior, risk-adjusted returns while insulating themselves from traditional market volatility. Far from being a fringe strategy, creative seller financing has quietly become one of the most reliable wealth-building instruments in modern real estate.
Moving Past the Bank: The Mechanics of Owner Financing
In a conventional deal, a buyer secures debt from an institutional mortgage lender, pays off the seller in full at closing, and remits monthly principal and interest payments to the financial institution.
Seller financing flips this dynamic. The property seller agrees to finance the purchase directly for the buyer. The parties draft a legally binding note and deed of trust (or mortgage) that outlines the repayment timeline, interest structure, down payment requirements, and default terms.
Instead of cashing out completely, the seller transforms real estate equity into a private paper asset. This structural shift converts a static piece of physical real estate into an income-generating, fixed-income instrument backed directly by the property itself.
Overcoming Profit Compression in Traditional Lending
Investors who rely strictly on traditional mortgages face systemic friction that degrades annual yields.
- Strict Underwriting vs. Direct Control: Traditional bank loans require standard 60-to-90-day underwriting schedules. Seller-financed deals eliminate institutional intermediaries, allowing closings to take place in a fraction of that time.
- Elimination of Fee Drag: Conventional debt incurs origination charges, appraisal delays, and broker markups. Direct owner financing removes these friction points, leaving more capital on the table for both parties.
- Superior Spread Capture: Institutional lenders cap their profit margins based on standardized market rates. Private note holders set their own loan terms, capturing premium interest rate spreads.
- Tax Protection: Outright equity sales trigger an immediate, lump-sum tax event. Seller financing provides multi-year deferral benefits under federal installment sale rules.
By eliminating institutional intermediaries, real estate owners retain direct control over deal parameters, creating profit margins that standard bank financing cannot replicate.
Key Advantages of Owner Financing for Real Estate Yields
1. Superior Interest Rate Margins and Capital Spread
When an investor finances a sale directly, they set the interest rate. Because they offer convenience, speed, and flexibility to buyers who may not fit the rigid box of traditional bank underwriting, sellers routinely command interest rates above prevailing institutional mortgage benchmarks.
Furthermore, if the investor holds existing low-cost debt on the asset, they can structure a wrapped loan agreement. This allows them to collect interest on the entire purchase value while continuing to service their underlying low-rate mortgage, creating significant cash-on-cash returns from the interest rate differential.
2. Tax Efficiency via Installment Sale Treatment
One of the largest silent erosion factors in real estate returns is the capital gains tax. When selling an asset outright, an investor faces an immediate, taxable event on the total equity realized in that tax year.
Under Section 453 of the Internal Revenue Code, seller-financed transactions are recognized as installment sales. Capital gains taxes are deferred and recognized proportionally over the lifetime of the loan as principal is repaid. This keeps capital working longer, compounding value over time rather than handing over a large portion of equity to tax authorities in a single year.
3. Down Payment Capitalization and Reduced Vacancy Costs
Traditional rental properties carry persistent risks: tenant turnover, property damage, maintenance overhead, and property management fees.
Under owner financing terms, the occupant is not a tenant they are an equitable owner. The buyer provides a non-refundable cash down payment, establishing substantial initial equity. Because the buyer holds equitable title, they assume full responsibility for maintenance, real estate taxes, and property insurance, eliminating operational expense leakage for the investor.
Structuring Owner Financing Terms for Maximum Risk Protection
Achieving elevated yields requires rigorous risk management. Elite investors engineer loan agreements with strict protective covenants to secure their capital position.
Establishing Protective Collateral Buffers
A proper seller-financed structure always requires a meaningful down payment percentage. Establishing a solid down payment buffer serves two strategic functions:
- It provides an immediate, non-taxable return of capital to the seller.
- It ensures the buyer has genuine skin in the game, drastically reducing default probabilities.
Short-Term Balloons vs. Amortization Cycles
To prevent long-term lockups of capital, experienced note holders often structure loans on a standard multi-decade amortization schedule with a balloon payment due in a shorter timeframe. This structure keeps monthly payments manageable for the buyer while guaranteeing that the investor recoups their principal equity relatively quickly through refinancing or resale.
Escrow and Loan Servicing Automation
Self-collecting monthly payments opens the door to administrative friction and late payment hassles. Best practices suggest hiring an independent third-party loan servicing company. For a small monthly fee (typically covered by the buyer), the servicer collects payments, manages escrow accounts for taxes and insurance, tracks principal depletion, and issues year-end tax documentation.
Real-World Strategic Execution
Consider an investor who acquired an asset and completed necessary renovations to prepare it for market.
Rather than listing the property on the open market for a standard cash sale or holding it as a high-maintenance rental, the investor offers seller financing with structured terms:
- Down Payment: Percentage-based equity contribution collected at closing
- Financed Capital: Remaining balance converted into a note
- Interest Rate: Fixed premium rate amortized over a multi-year term
- Monthly Obligation: Fixed monthly principal and interest remittance
By executing this structure, the investor recoups capital instantly via the down payment. They lock in predictable monthly passive cash flow without handling maintenance calls, tenant turnover, or property management fees. If the buyer defaults, the investor retains the down payment, keeps all accrued interest, and regains ownership of the physical asset through standard legal procedures.
Leading platforms in the private note space, such as WeHome500, demonstrate how streamlining creative acquisition and disposition structures allows market participants to maximize capital efficiency without taking on traditional banking overhead.
The Future Outlook for Private Real Estate Finance
As financial markets become increasingly digitized and institutional lending criteria remain rigid, private seller financing will continue to gain traction. Investors who master note creation, debt structuring, and private contract mechanics gain a distinct competitive edge.
By shifting perspective from landlord to lien holder, investors unlock superior yields, minimize tax drag, eliminate property management headaches, and build truly passive, high-return real estate portfolios.
Frequently Asked Questions
Q1 What happens if a buyer defaults on an owner-financed deal?
Because the transaction is secured by a deed of trust or mortgage note, the seller retains the right to initiate legal foreclosure proceedings, recover the physical property, and retain the buyer’s down payment and previous principal payments.
Q2 Can an investor seller-finance a property if they have an existing mortgage?
Yes, using a “wrap-around” mortgage structure. However, investors must navigate the original lender’s “due-on-sale” clause carefully, typically by using legal trusts or obtaining lender permissions.
Q3 Who is responsible for property taxes and maintenance under owner financing?
The buyer holding equitable title assumes full financial and operational responsibility for real estate taxes, property insurance, and ongoing repairs.
Q4 How does an investor handle loan administration for seller-financed properties?
Best practices dictate using a licensed, third-party loan servicing company to collect monthly payments, handle tax escrows, issue annual statements, and manage collection notices automatically.
Q5 Can a seller-financed note be sold for cash later?
Yes. Private real estate mortgage notes are tradable paper assets. An investor can sell the full note or a portion of its future payments (a partial) on the secondary mortgage market for an immediate cash lump sum.