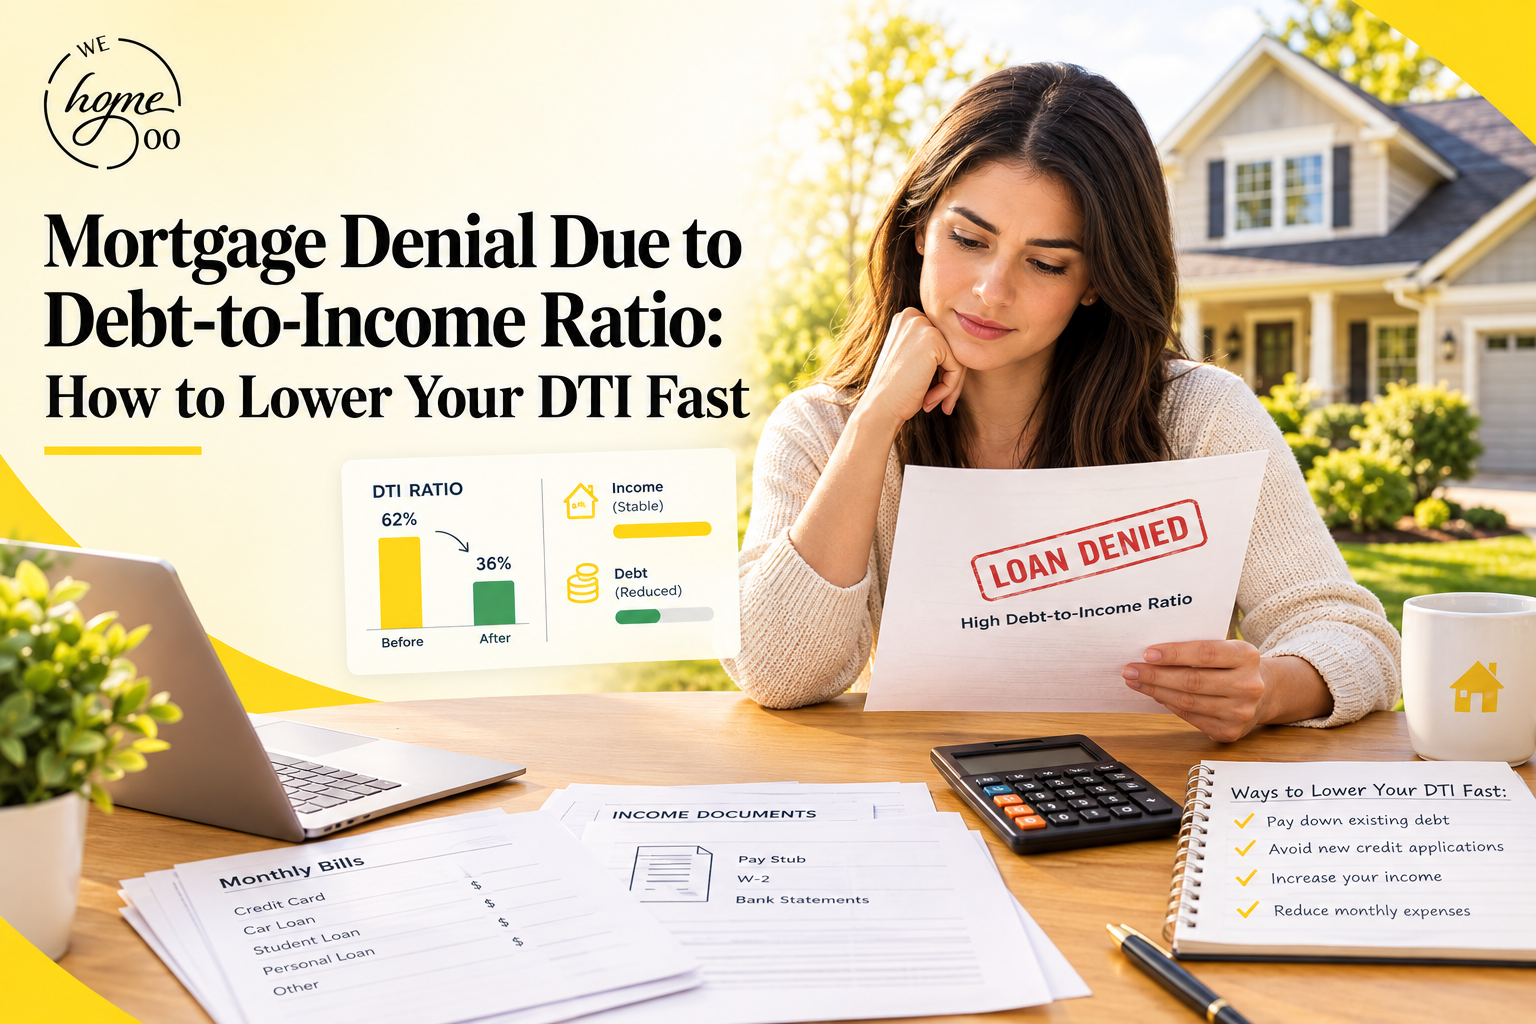
A high debt-to-income ratio can contribute to mortgage denial because lenders use DTI to evaluate a borrower’s ability to manage additional monthly debt. Lowering DTI may involve paying off debts with significant monthly payments, increasing qualifying income, avoiding new obligations, or reducing the proposed mortgage payment. However, DTI limits vary by lender and loan program, so borrowers should review the specific underwriting requirements that apply to their application.
Introduction
A mortgage application can look strong on paper and still face a mortgage denial because the borrower’s debt is too high compared with their income.
Debt-to-income ratio, or DTI, is one of the measures lenders use to assess whether a borrower can handle new monthly debt. The Consumer Financial Protection Bureau defines DTI as total monthly debt payments divided by gross monthly income. Different loan products and lenders can use different DTI limits.
That flexibility matters. There isn’t one universal number that guarantees mortgage approval.
The good news is that DTI isn’t necessarily permanent. Borrowers can often improve it by reducing qualifying monthly debt, increasing documented income, changing the loan amount, or allowing certain debts to be paid off before applying. And if a traditional lender isn’t the right fit right now, buying a home through owner financing is one alternative worth understanding while you work on your numbers.
What DTI Means for Mortgage Approval
DTI compares the monthly debt obligations counted by the lender with gross monthly income.
The basic calculation is:
DTI = Total Monthly Debt ÷ Gross Monthly Income × 100
For example, imagine a borrower earns $7,000 in gross monthly income and has $2,800 in qualifying monthly debt.
$2,800 ÷ $7,000 = 40% DTI
The calculation can include the proposed housing payment along with other qualifying debts. Depending on the underwriting rules, lenders may consider obligations such as auto loans, student loans, credit card payments, alimony, child support, and other debts.
Why a High DTI Can Create Problems
A high DTI suggests that a larger share of monthly income is already committed to debt.
That doesn’t automatically mean the borrower cannot afford a home. It means the lender’s underwriting model may view the additional obligation as carrying more repayment risk.
A borrower with a high DTI may therefore encounter:
- A request for additional documentation
- A lower approved loan amount
- Different loan eligibility
- A need to reduce existing debt
- A home loan rejection
Lenders can also consider factors beyond DTI. CFPB regulations allow creditors to consider additional factors relevant to a borrower’s ability to repay.
How Much DTI Is Too High?
There’s no single DTI threshold that applies to every mortgage.
For example, Fannie Mae’s current Selling Guide states that manually underwritten loans generally have a maximum total DTI of 36%, with an increase to 45% when specified credit score and reserve requirements are met. For loans underwritten through Desktop Underwriter, the maximum allowable DTI is 50%, subject to applicable requirements and exceptions.
Those figures should not be treated as universal mortgage rules.
The actual threshold can depend on the loan program, underwriting method, lender requirements, credit profile, income, reserves, and other factors.
DTI Isn’t the Whole Application
Mortgage underwriting is broader than one ratio.
Freddie Mac notes that lenders may review employment, income, assets, debts, credit history, and other information when evaluating a mortgage application.
That means lowering DTI can help, but it doesn’t guarantee approval.
Ways to Lower DTI Before Applying
If your DTI is preventing mortgage approval, focus on changes that affect the monthly numbers used by underwriting.
1. Pay Down High Monthly Debts
One of the most direct approaches is reducing debt with meaningful monthly payments.
Consider a borrower with:
- $7,000 gross monthly income
- $2,800 monthly debt
- 40% DTI
If a $400 monthly obligation is eliminated, qualifying debt falls to $2,400.
$2,400 ÷ $7,000 = 34.3% DTI
The important point is that DTI responds to monthly obligations, not simply the total balance owed.
A large debt with a relatively small monthly payment may have less immediate impact on the ratio than a smaller debt carrying a large monthly payment.
2. Avoid Taking on New Debt
Applying for another auto loan, financing furniture, or opening new credit before closing can complicate underwriting.
A new monthly obligation can increase DTI. It can also trigger additional underwriting review.
Keeping your financial position stable during the mortgage process is generally sensible.
3. Increase Documented Income
Reducing debt isn’t the only way to improve the ratio.
If qualifying gross income increases while monthly debt remains unchanged, DTI decreases.
However, borrowers shouldn’t assume that every source of income can immediately be used for mortgage qualification. Lenders generally need income to be documented and meet applicable underwriting requirements. CFPB rules require creditors to verify relevant income or assets using reasonably reliable third-party records in covered transactions.
Potentially relevant income can include employment income and certain other qualifying sources, depending on the loan program and documentation.
4. Consider a Lower Loan Amount
Sometimes the problem isn’t the existing debt alone. The proposed mortgage payment may be pushing the overall ratio beyond the lender’s limit.
A lower purchase price or larger down payment can reduce the proposed mortgage amount and potentially reduce the monthly housing payment.
That can change the DTI calculation.
Choosing a more modest property type can also change the math. Options like tiny homes, mobile homes, and manufactured homes often come with lower price points and, in turn, lower monthly housing payments.
Still, a larger down payment should not be pursued at the expense of leaving yourself without adequate cash reserves. The CFPB recommends considering what payment fits comfortably within your broader financial situation rather than focusing only on the maximum amount a lender might approve.
What to Do After a DTI-Based Mortgage Denial
A denial isn’t the time to guess which number caused the problem.
Start by reviewing the lender’s explanation and the information used in the application.
Check the Numbers
Verify:
- Gross monthly income
- Credit card payments
- Auto loans
- Student loans
- Personal loans
- Existing mortgages
- Child support or alimony
- Proposed housing payment
- Other obligations included by the lender
An error in reported income or debt can materially affect DTI.
Ask Which Debts Were Counted
The debt calculation used for underwriting isn’t always identical to the personal budget you create at home.
A lender may have specific rules for determining which obligations count and what payment amount should be used.
Understanding the exact calculation is more useful than simply trying to reach an arbitrary percentage.
Review Your Credit Reports
Credit reports can contain outdated balances, incorrect payment information, or accounts that don’t belong to you.
Because lenders use credit and debt information during underwriting, checking your reports before another application can help identify potential discrepancies.
Don’t close accounts or make major credit changes solely to improve your application without understanding the possible consequences.
A Simple Example of Improving DTI
Consider a borrower earning $8,000 per month.
Their qualifying monthly debts total $3,600.
That produces a DTI of:
$3,600 ÷ $8,000 = 45%
Suppose the borrower pays off a debt with a $500 monthly payment.
New monthly debt:
$3,600 − $500 = $3,100
New DTI:
$3,100 ÷ $8,000 = 38.75%
That is a meaningful change.
Notice that the improvement came from eliminating a monthly obligation, not necessarily from paying off the entire largest debt.
This is why borrowers should examine the monthly payment attached to each obligation when planning DTI improvements.
Exploring Alternatives While You Improve Your DTI
A denial can feel like a dead end, but a bank mortgage isn’t the only route to ownership. Some buyers use the time while they lower their DTI to explore other paths, such as rent-to-own mobile homes, where a portion of payments may build toward ownership, or owner-financed homes that don’t depend on a conventional lender’s approval process.
Terms vary by property and seller, so review any agreement carefully and consider getting professional advice before signing. If you’d like to talk through your options, you can book a call with the WeHome500 team.
Don’t Chase a Ratio at the Expense of Affordability
Lowering DTI can improve mortgage qualification, but qualification isn’t the same as financial comfort.
The CFPB specifically advises borrowers to focus on what they can afford within their broader financial priorities rather than simply borrowing the maximum amount a lender is willing to provide.
A borrower might technically qualify after reducing DTI but still have limited cash flow for:
- Emergency savings
- Home maintenance
- Insurance
- Property taxes
- Utilities
- Retirement contributions
- Unexpected expenses
The better question isn’t only, “Can I get approved?”
It’s also, “Will this payment still work when something unexpected happens?”
Final Takeaway
A mortgage denial caused by DTI doesn’t necessarily mean homeownership is permanently out of reach.
DTI is a calculation based largely on monthly obligations and qualifying income. That gives borrowers several potential ways to improve their position: reduce qualifying monthly debt, avoid new obligations, strengthen documented income, or reconsider the size of the proposed mortgage.
Most importantly, don’t rely on a single percentage as a universal approval rule. Mortgage underwriting varies by loan type and lender, and current Fannie Mae guidance demonstrates that different underwriting paths can have different DTI limits.
A stronger mortgage application begins with accurate numbers. Once you know exactly what is driving the ratio, you can make financial decisions based on the actual problem rather than trying to guess what a lender wants to see.
Have questions about your next step? Contact WeHome500 or explore more homeownership guides on our blog.
FAQs
Can high DTI cause mortgage denial?
Yes. A high DTI can affect mortgage eligibility when it exceeds the applicable underwriting requirements.
What is DTI?
DTI compares qualifying monthly debt payments with gross monthly income.
How can I lower DTI quickly?
Paying off or reducing debts with significant monthly payments can lower the ratio.
Does paying off a credit card lower DTI?
It can, particularly when paying off the balance eliminates or reduces the monthly payment counted by the lender.
Can I get a mortgage after a home loan rejection?
Potentially. The next step is to identify why the application was denied and determine whether the underlying issue can be corrected before applying again. In the meantime, you can explore owner financing options as an alternative path to ownership.